The health coverage of an expatriate senior is not limited to the choice between CFE and first euro insurance. The zoning of reimbursements, age limits for subscription, and recent developments in the CFE fundamentally change the decision-making process. Here, we detail the technical points that truly determine the quality of protection.
CFE Zoning and Actual Out-of-Pocket Costs for Expatriate Seniors
The CFE now classifies countries into five distinct reimbursement zones. The rates applied depend on the zone where care is provided, not the country of administrative residence. This distinction changes everything for a retiree living in Morocco but undergoing surgery in France or Thailand.
In high medical cost zones, hospital reimbursement caps remain indexed to scales that do not keep pace with local inflation of clinical rates. The out-of-pocket costs for hospitalization can then represent a significant portion of the bill, especially for surgical procedures or extended stays in intensive care.
We recommend checking the pricing grid zone by zone before any subscription. A senior residing in Portugal but needing to consult regularly in mainland France does not fall under the same scale depending on the actual location of care. Cross-referencing this data with the guarantees of a supplementary plan allows for finding information for seniors on France Expat Santé that details suitable combinations for each profile.
CFE Teleconsultation: What Changes with the Extension to Seniors
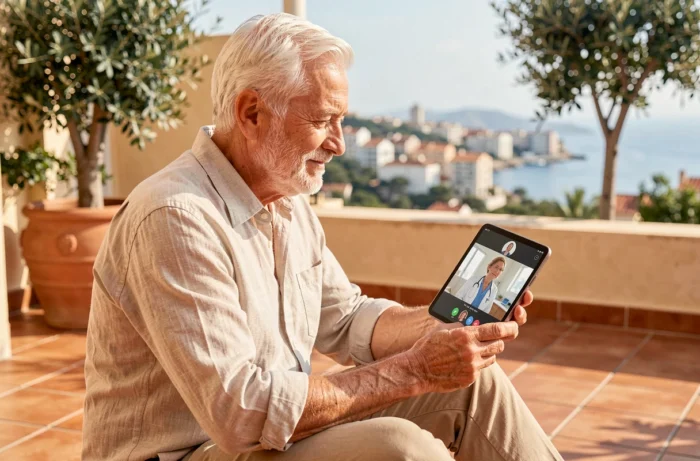
The teleconsultation experiment launched in 2025 for insured individuals aged 50 to 70 in Morocco, Tunisia, and Senegal was extended in 2026. The covered age range now goes up to 40-85 years, and new countries have joined the program: Côte d’Ivoire, Mauritius, Cambodia.
For a senior over 70 residing in one of these countries, this provides direct access to a French-speaking doctor without significant travel or upfront costs. The service also reduces reliance on local emergency services, which are often expensive and poorly reimbursed by the CFE alone.
The technical interest lies in the integration with existing guarantees. CFE teleconsultation does not replace a supplementary plan for physical procedures (imaging, biology, surgery), but it covers the management of chronic conditions common among expatriate seniors: hypertension, type 2 diabetes, post-stroke follow-up.
First Euro Insurance or CFE Supplement: Choosing Criteria for a Senior
The debate between first euro insurance and CFE membership supplemented by a mutual insurance plan hinges on three specific parameters.
- Age at subscription: several insurers refuse new memberships beyond 70 or 75 years, or apply surcharges that make the first euro option more expensive than a CFE + supplementary plan. Check the age limit and lifelong guarantee before any commitment.
- The country of residence and frequency of returns to France: a retiree who returns several months a year to mainland France should maintain their rights to French social security and supplement with an international mutual insurance plan.
- The level of local hospital coverage: in countries where the public system offers adequate coverage (Portugal, Greece under bilateral agreements), high-end first euro insurance may be an unnecessary expense. Conversely, in countries without agreements or with limited hospital infrastructure, the first euro with repatriation included becomes the only viable option.
International Hospital Third-Party Payment Expected in 2027
The CFE has announced new collective health contracts that will include a hospital third-party payment system and assistance services, expected to be available starting in 2027. For seniors facing upfront costs of several thousand euros during hospitalizations abroad, this development will remove a major financial obstacle.
In the meantime, we observe that the most protective solution remains the combination of CFE + supplementary plan that includes direct coverage with partner establishments. Contracts offering a hospital network with third-party payment agreements avoid upfront costs, a critical point for retirees whose available cash flow is often limited.
Rights to French Social Security During Temporary Returns
The conditions for maintaining rights to the Vitale card for care during temporary stays in mainland France depend on the contribution history in France. When these conditions are not met, the Vitale card is deactivated and care in France is no longer covered by health insurance.
This rule has a direct impact on the choice of international coverage. A senior who does not meet this condition must necessarily subscribe to insurance that also covers care in France, which not all first euro plans offer. Checking the “care in the country of nationality” clause of the contract is a reflex to adopt before signing.
Pension Coordination and Health Coverage
Retirees who have worked in several European Union countries benefit from the totalization of quarters for calculating their rights. Each country pays its share of the pension in proportion to the periods contributed. However, health coverage depends on the country of residence, not on the country that pays the highest pension.
A French retiree living in Portugal falls under the Portuguese health system, even if most of their pension comes from the CNAV. The S1 form allows for the transfer of health insurance rights to the country of residence, but the quality of coverage then depends on the local system.
The choice of expatriation country is not limited to the cost of living or taxation. Actual access to specialized care, the availability of French-speaking practitioners, and the level of reimbursement in the relevant CFE zone weigh as much as the amount of the net pension. A rigorous assessment of these three axes avoids unpleasant surprises once the relocation is effective.